A simple model of asset demand
Take an investor with Epstein–Zin preferences who chooses bonds \(B\) and stocks \(S\), where equity payouts carry risk \(\theta\) with variance \(\sigma^2\). With unit elasticity of intertemporal substitution, the demand for equities is
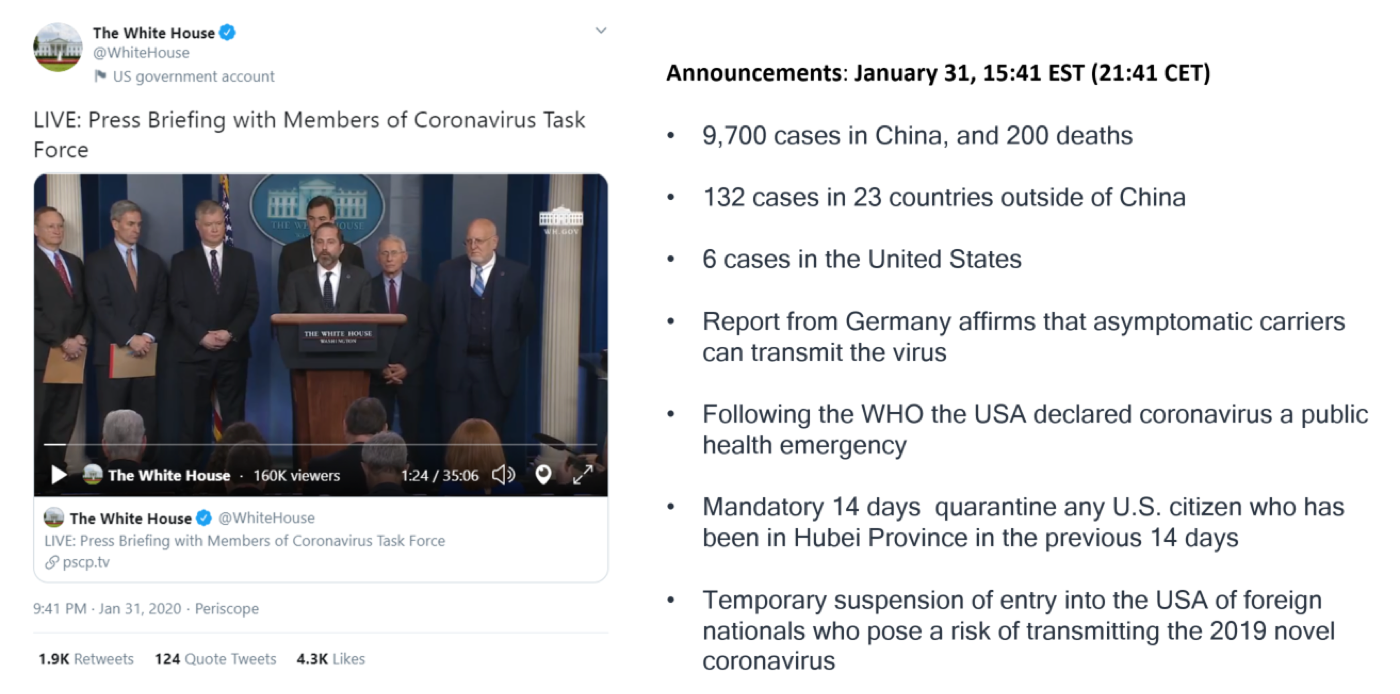
An announcement is an unbiased signal about \(\theta\) that lowers the posterior variance \(\sigma^2\). If investors care about when uncertainty is resolved (\(\gamma>1\)), announcements should on average move demand from bonds to equities. Equity prices should rise. Bond prices should stay flat if bond supply is flat, and dip if it slopes upward.
To test this, we compare the minute-by-minute behavior of each asset around announcements with its behavior at the same clock time before the epidemic (\(Z_t\)). We fit a quadratic in time that is allowed to break at the announcement time \(t^*\):
Standard errors are HAC-adjusted. A country's epidemic period starts on the day it passes 100 confirmed cases.